A sanction letter is not a loan. Between the two sit two reports, prepared by two different people, and a file fails at whichever is weaker.
The legal opinion
An empanelled advocate reads the title. They are looking for an unbroken chain of ownership, a clean revenue record, and the absence of anything that would make the bank's charge unenforceable.
What stops files here:
- Mutation not completed. The record still reads a previous owner. This is the single most common reason a file stalls in both states.
- A gap in the chain — an inheritance that was never formalised, a sale that was never registered.
- Agricultural classification where the intended use is residential.
- Section 118 unresolved on Himachal land.
The technical valuation
A separate valuer visits, measures and reports. They are establishing what the bank could recover, not what you agreed to pay.
What moves that number down:
- Carpet area against what the brochure claims. The valuer measures.
- Age and condition. A structure has a remaining life, and lending is set against it.
- Approach. A property reachable only by an unmetalled track is valued accordingly, which is a real factor on hill properties.
- Sanction. Unapproved construction is often excluded from the valuation altogether — the land is valued and the building is not.
The gap that surprises people
Your loan is set against the lower of the agreed price and the valuation, and the margin is applied to that. A valuation below your price does not reduce the price. It increases the cash you must find, and it lands late in the process.
What to do about it
- Settle the mutation before you apply, not during.
- Ask the seller for the sanctioned plan and compare it with what is standing.
- Where the property is unusual — hill plot, old structure, part-commercial — expect a conservative valuation and arrange the file accordingly.
- If a valuation comes in low and you believe it is wrong, ask for the comparables it used. Sometimes they are from the wrong pocket.
What we do
We read the revenue record before a property reaches a shortlist, which removes the most common cause of a stalled file before a buyer has spent anything on it.
Related notes
16 October 2026 · 6 min read
Buying a prelaunch flat in Punjab: the RERA checks to make before you pay a token
Prelaunch is where the best unit choice is — and where the paperwork is thinnest. Four checks that take an afternoon, using Elegancia on NH-05 as a live example of a project still at that stage.
16 October 2026 · 5 min read
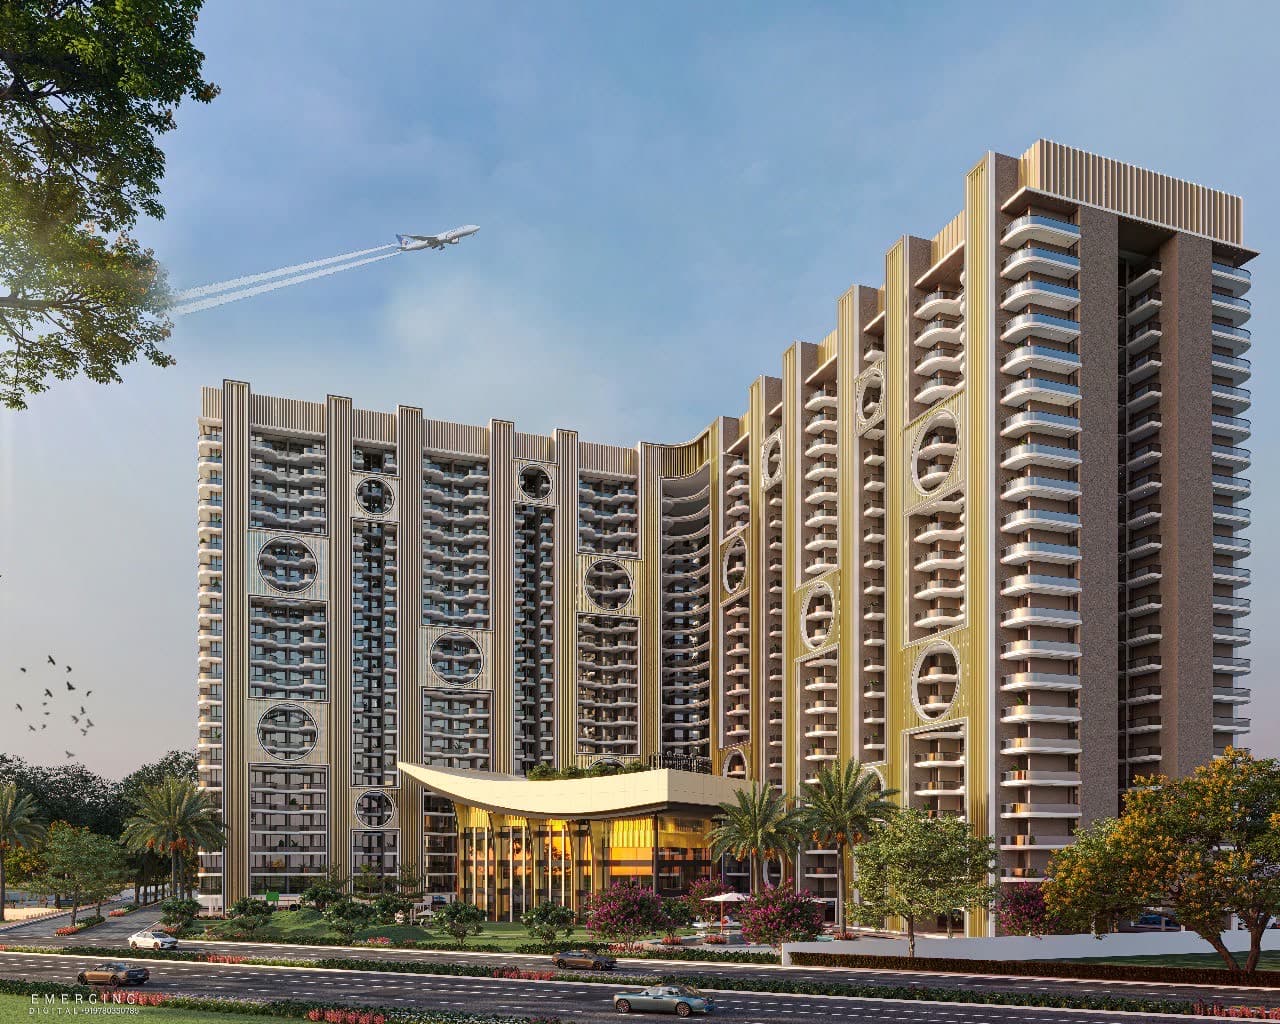
Elegancia on NH-05: what Divya Builders has announced, and what has not been yet
A 14-acre mixed-use high-rise address on the Kharar–Ludhiana Highway, near Chandigarh University. Here is what the developer's own material commits to, what it leaves open, and what we would want in writing before anyone pays a token.
16 October 2026 · 5 min read
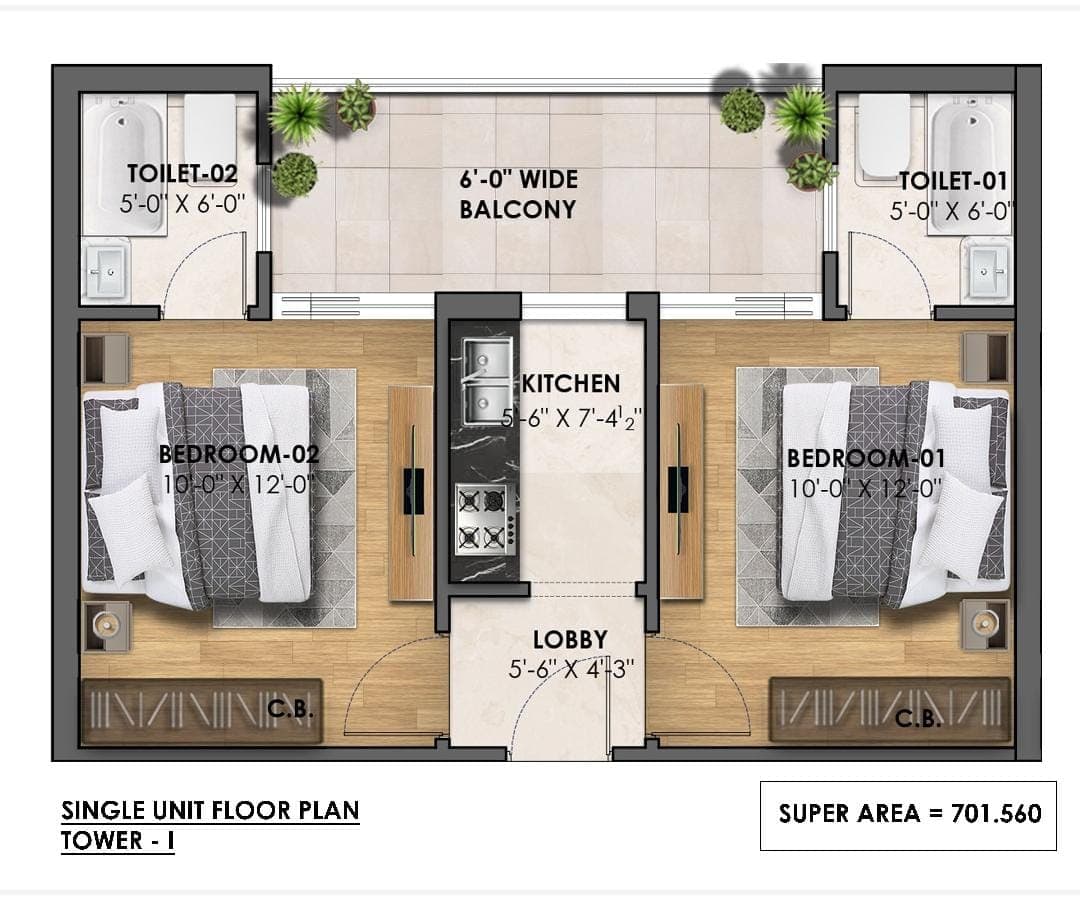
Super area or carpet area? Reading an Elegancia floor plan
The Tower I plan at Elegancia states a super area of 701.56 sq ft. The rooms drawn on it add up to about 364 sq ft. Here is where the rest goes, and the one question to ask before comparing prices.